

Buying your first home in Davis County or Weber County is an exciting milestone, but it often comes with a lot of uncertainty and important financial decisions. One of the first questions most buyers ask is "what can I afford," closely followed by "what kind of loans are there" and "how much do I need to make to buy a house."
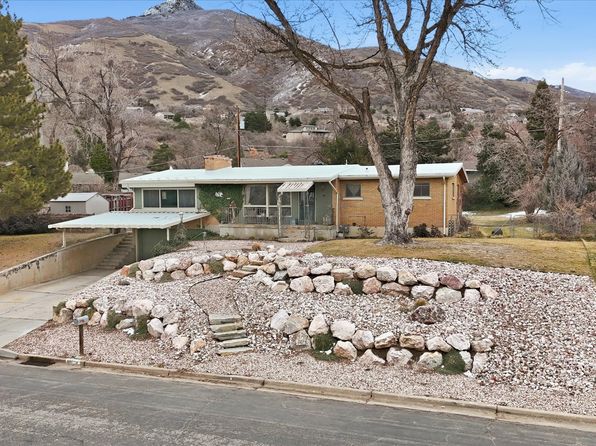 Weber County, Utah — Home to affordable single family homes and townhouses for first time buyers. Photo: Zillow Weber County
What Can I Afford in Davis and Weber Counties
Home prices in Davis County and Weber County vary by city, neighborhood, and property type, but both counties continue to offer more accessible entry points than many other parts of Utah. Whether you're looking in Layton, Clearfield, or Syracuse, there are options for first time buyers at different price points.
Recent listing data for Davis and Weber Counties shows that single family homes still make up the majority of available inventory, accounting for just over seventy percent of new listings year to date. Townhomes represent a growing share of the market, while condos remain a smaller but important option for first time buyers looking to lower their price point.
Your affordability is based on several key factors:
- Gross household income
- Monthly debt obligations
- Credit score
- Down payment funds
- Loan program used
This is where FHA and Conventional loans can lead to very different answers to the question "what can I afford."
What First Time Buyers Can Expect in Davis and Weber Counties
Most homes you will see in Davis and Weber Counties are single family properties, which means strong competition for well priced homes in popular neighborhoods like Ogden and Roy. Townhomes are becoming more common and often provide a more affordable path into homeownership with less maintenance. Condos are less available but can offer the lowest purchase prices, though buyers should plan for homeowners association fees and financing guidelines. Staying flexible with property type can improve your chances of finding the right first home.
New Listings by Dwelling Type – Year to Date
| Property Type | Percentage of Market | Average Price per Sq Ft |
|---|---|---|
| Single Family | 70.13% | $258 |
| Townhouse | 18.04% | $245 |
| Condo | 4.06% | $259 |
| Other | 7.77% | Varies |
Source: MLS data for Davis and Weber Counties, year to date 2026. Data reflects new listings only. All data is obtained from various sources and should be independently verified for accuracy.
What Kind of Loans Are There for First Time Home Buyers
There are several loan programs available, but FHA and Conventional loans are the most commonly used by first time buyers in Davis and Weber Counties.
📋 FHA Loans
FHA loans are insured by the Federal Housing Administration and are designed to help buyers who may have limited savings or less than perfect credit.
📋 Conventional Loans
Conventional loans are not government insured and usually require stronger financial qualifications, but they often provide lower costs over time. These loans are backed by Fannie Mae and Freddie Mac.
Understanding the differences between these two loan types is essential when planning your home purchase.
FHA Loans Explained for Northern Utah Buyers
Advantages of FHA Loans
FHA loans are popular with first time home buyers because they are more flexible. Key benefits include:
- Lower minimum credit score requirements
- Down payments as low as three point five percent
- More lenient debt to income guidelines
For buyers asking "how much do I need to make to buy a house," FHA loans often allow qualification with a lower income compared to other programs.
Drawbacks of FHA Loans
Despite their flexibility, FHA loans come with important tradeoffs. Potential downsides include:
- Mortgage insurance required for the life of the loan in most cases
- Lower loan limits that may restrict options in higher priced neighborhoods
- Stricter property condition requirements
In competitive markets within Davis County and Weber County, these property standards can sometimes make FHA offers less attractive to sellers.
Conventional Loans Explained for First Time Buyers
Advantages of Conventional Loans
Conventional loans are often a strong choice for buyers with stable income and solid credit. Benefits include:
- Private mortgage insurance that can be removed once sufficient equity is reached
- Fewer restrictions on property condition
- Often lower monthly costs over the long term
Many first time buyers are surprised to learn that some Conventional programs allow down payments as low as three percent.
Drawbacks of Conventional Loans
Conventional loans are less forgiving in certain areas. Challenges include:
- Higher credit score expectations
- Tighter debt to income ratios
- Less flexibility with recent credit issues
For buyers early in their careers or carrying student loan debt, FHA financing may feel more attainable.
FHA vs Conventional: Which Is Better in Davis and Weber Counties
There is no universal answer, but the right choice depends on your financial profile and goals.
| Factor | FHA Loan Gov't Backed | Conventional Loan Standard |
|---|---|---|
| Minimum Down Payment | 3.5% | 3% (some programs) |
| Credit Score Needed | Below mid 600s acceptable | Strong score preferred |
| Mortgage Insurance | Required, usually for life of loan | PMI can be removed after reaching 20% equity |
| Property Condition | Stricter requirements | Fewer restrictions |
| Long Term Cost | Higher due to permanent insurance | Lower once PMI is removed |
| Best For | Limited savings, lower credit, more flexibility needed | Stable income, strong credit, long term savings |
An FHA loan may be a better fit if your credit score is below the mid six hundreds, you have limited savings for a down payment, your monthly debts are higher, or you need more flexibility to qualify.
A Conventional loan may be the better option if your credit score is strong, your income is stable and predictable, you want lower long term monthly payments, or you plan to stay in the home for many years.
This decision directly affects "what can I afford" in today's Davis and Weber County housing market.
How Much Do I Need to Make to Buy a House in Davis or Weber County
Income requirements depend on the home price, interest rate, loan type, and your existing debts. The Consumer Financial Protection Bureau offers helpful tools for understanding mortgage affordability.
Local data shows that average and median list price per square foot in Davis and Weber Counties has declined year over year, which can help improve affordability for first time buyers entering the market now.
As a general example, FHA loans may allow buyers to qualify with lower income levels, though monthly payments may be higher due to mortgage insurance. Conventional loans may require higher income upfront, but monthly costs are often lower over time.
The most accurate way to determine "how much do I need to make to buy a house" is to compare loan scenarios with a lender who understands the Davis and Weber County markets.
Final Thoughts for First Time Buyers in Northern Utah
FHA and Conventional loans both play an important role in helping first time buyers achieve homeownership in Davis County and Weber County.
By understanding what kind of loans are there, what can I afford, and how much do I need to make to buy a house, you can move forward with clarity and confidence rather than guesswork. Learn more about Davis County and Weber County to understand the communities you're considering.
Working with a knowledgeable local real estate professional and lender ensures you choose a loan strategy that fits both your finances and the realities of the Northern Utah housing market.
Frequently Asked Questions
Ready to Start Your Home Search?
Connect with Jordan Smith, a local Utah realtor who specializes in Davis and Weber County. Jordan can connect you with qualified lenders and help you explore both FHA and Conventional loan options based on your situation.
Talk to a Local RealtorNo obligation to move forward. See our Google reviews
 Wasatch Front Regional MLS - Salt Lake Board of REALTORS® All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties
